Before comparing two numbers, ask how each was produced. The benchmark, risk-free return, observation frequency, dates, fee treatment and annualization method can change the answer. A familiar metric calculated on incompatible inputs is not a fair comparison.
Use the measures together to investigate exposures and outcomes, while keeping their limits visible. A high R-squared does not validate a fund, a low beta does not eliminate risk and a positive estimated alpha is not proof that a manager has skill.
Start with the Return Series
Define whether the observations are monthly, quarterly or annual and whether returns include reinvested distributions and fund operating expenses. Distinguish a fund return from an investor return affected by contributions, withdrawals, loads and personal taxes.
Record the lookback and update convention. Providers can use different periods and methods; there is no universal requirement that every risk measure use 36 observations or update quarterly. A statistic from one lookback should not be compared casually with another.
Annualization also needs a convention. Square-root-of-time scaling relies on assumptions about the return process; serial dependence can affect the relationship. Check the documented method rather than assuming that every annualized figure measures the same thing.
Standard Deviation Measures Dispersion, Not Every Risk
Sample standard deviation measures how far returns lie from their sample mean. Under the conventional sample formula, square each observation's deviation from the mean, add those squared deviations, divide by one less than the observation count and take the square root.
Equal-sized positive and negative deviations contribute equally. That symmetry does not mean that any two return paths with gains and losses have the same standard deviation. The full set of observations matters.
Volatility is also different from maximum drawdown, permanent loss, liquidity risk or the risk of failing to fund a bill. An infrequently valued investment can show a smooth reported series without being easy to sell at that value. A portfolio with low historical volatility can still have an unacceptable exposure to a rare event.
Diversification can reduce dependence on individual issuers when weights and relationships permit it. It does not create a universal equity-volatility floor or establish that twenty and five hundred stocks have identical interest-rate exposure. Common-factor risk depends on holdings and weights, and its realized return is not guaranteed compensation.
Distinguish a percentage reduction in standard deviation from a reduction in variance or company-specific risk. They are different quantities. A claim about a fixed stock count also needs its sample and portfolio construction; it is not a universal client adequacy rule.
Beta Is a Regression Slope
For a simple one-benchmark model, use matched fund and benchmark returns above the same risk-free return. Write the relationship as: fund excess return equals alpha plus beta times benchmark excess return plus a residual.
The fitted beta is the sample covariance of the two excess-return series divided by the sample variance of benchmark excess returns. It describes linear sensitivity within that sample. Zero benchmark-excess variance makes this slope formula undefined. The benchmark has beta one relative to itself when its variance is nonzero; that does not make the S&P 500 the appropriate benchmark for every investment.
A beta of 1.2 does not promise that every market movement produces a fund movement 20% larger. The intercept, residual outcome, changing holdings and nonlinear exposures matter. Options, leverage and changing market relationships can make a simple historical slope especially incomplete.
Nor does a lower beta automatically make a holding suitable for a cash need. It can describe different exposures, including a negative relationship to the selected benchmark. Compare the underlying risks and the client's whole portfolio before changing investments.
R-Squared Describes Fit, Not a Truth Test
In a one-predictor regression with an intercept, R-squared is the squared sample correlation between the matched excess-return series. It can be stated from zero to one or as a percentage. The sign of correlation disappears when squared. A constant fund-excess series makes the usual correlation and squared-correlation formula undefined.
It describes the proportion of sample variation explained by that fitted model. It does not establish causation, future stability, the right benchmark or the precision of a coefficient by itself. Sample length, residual variation, benchmark variation and model specification matter.
There is no universal R-squared cutoff that turns beta or alpha into truth above it and noise below it. A low-fit relationship may still contain a meaningful estimated slope, while a high-fit relationship can be economically unsuitable or unstable. Examine the model and uncertainty rather than substituting a threshold for analysis.
Alpha Requires the Risk-Free Return and Model Scope
Under the simple excess-return regression, the fitted intercept is mean fund excess return minus beta times mean benchmark excess return. Equivalently, it is mean fund return minus [mean risk-free return plus beta times mean benchmark excess return]. Use consistent periods and conventions.
Multiplying the benchmark's total return by beta generally omits [one minus beta] times the mean risk-free return. The calculations coincide when that omitted term is zero, including when beta is one or the mean risk-free return is zero. A more complex factor model can produce a different alpha because it explains different exposures.
Estimated alpha is the return the chosen model leaves unexplained. It can reflect omitted risks, luck, measurement error or model mismatch as well as possible skill. An appropriate benchmark and an estimated alpha, whether positive, zero or negative, are starting points for an investigation, not proof of prospective manager ability.
A Complete Hypothetical Sample
Use four invented annual observations. Assume a constant 2% annual risk-free return. The fund returns below are assumed net of fund operating expenses, before personal taxes, loads and other investor costs. They are not observed fund data or a recommendation.
| Year | Benchmark return | Fund A return | Fund B return |
|---|---|---|---|
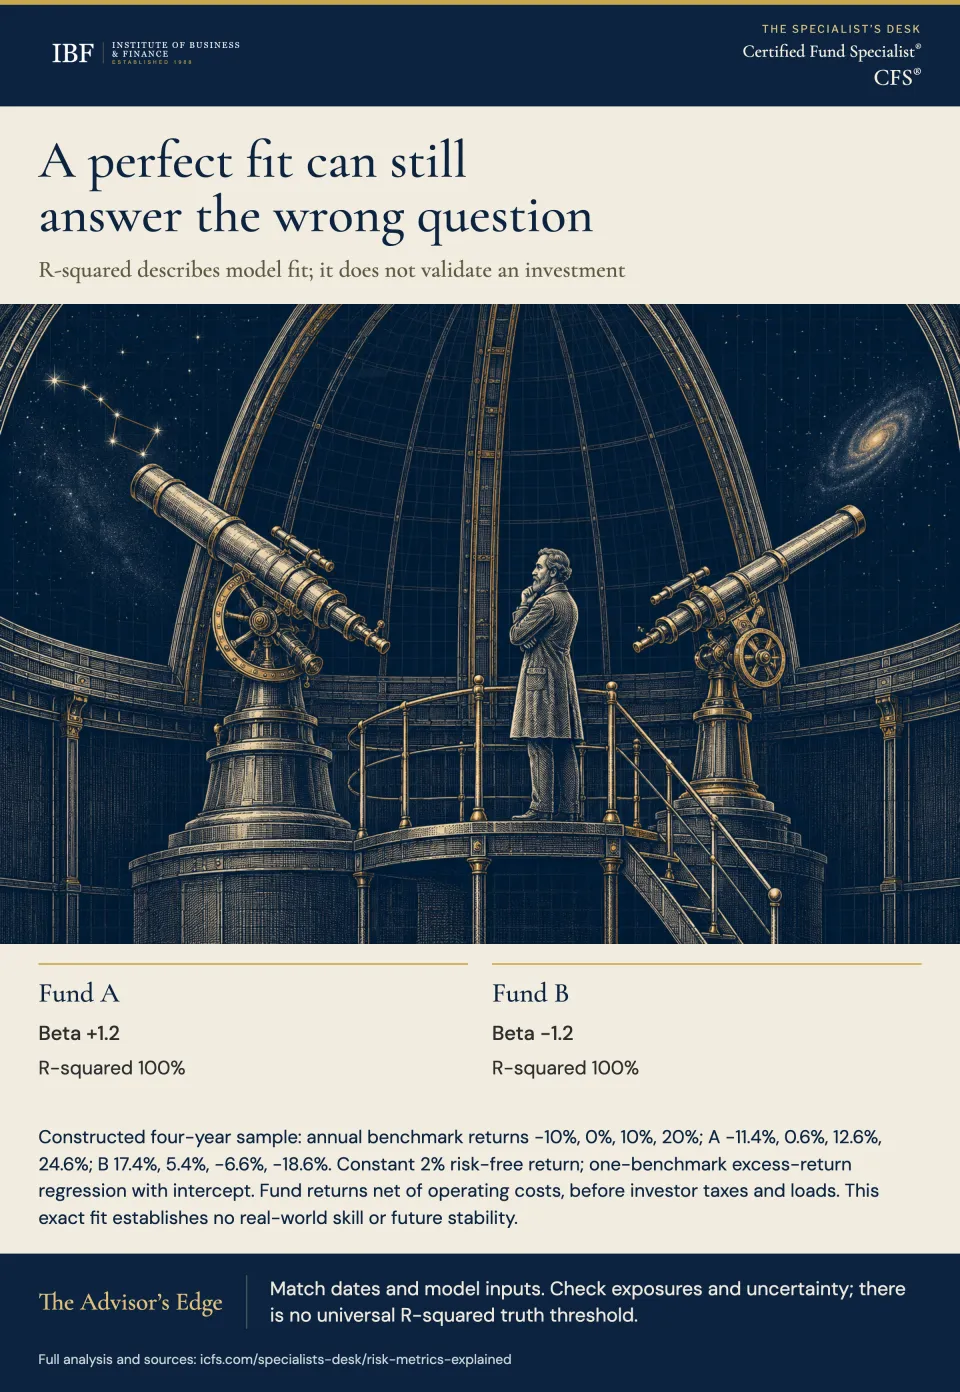
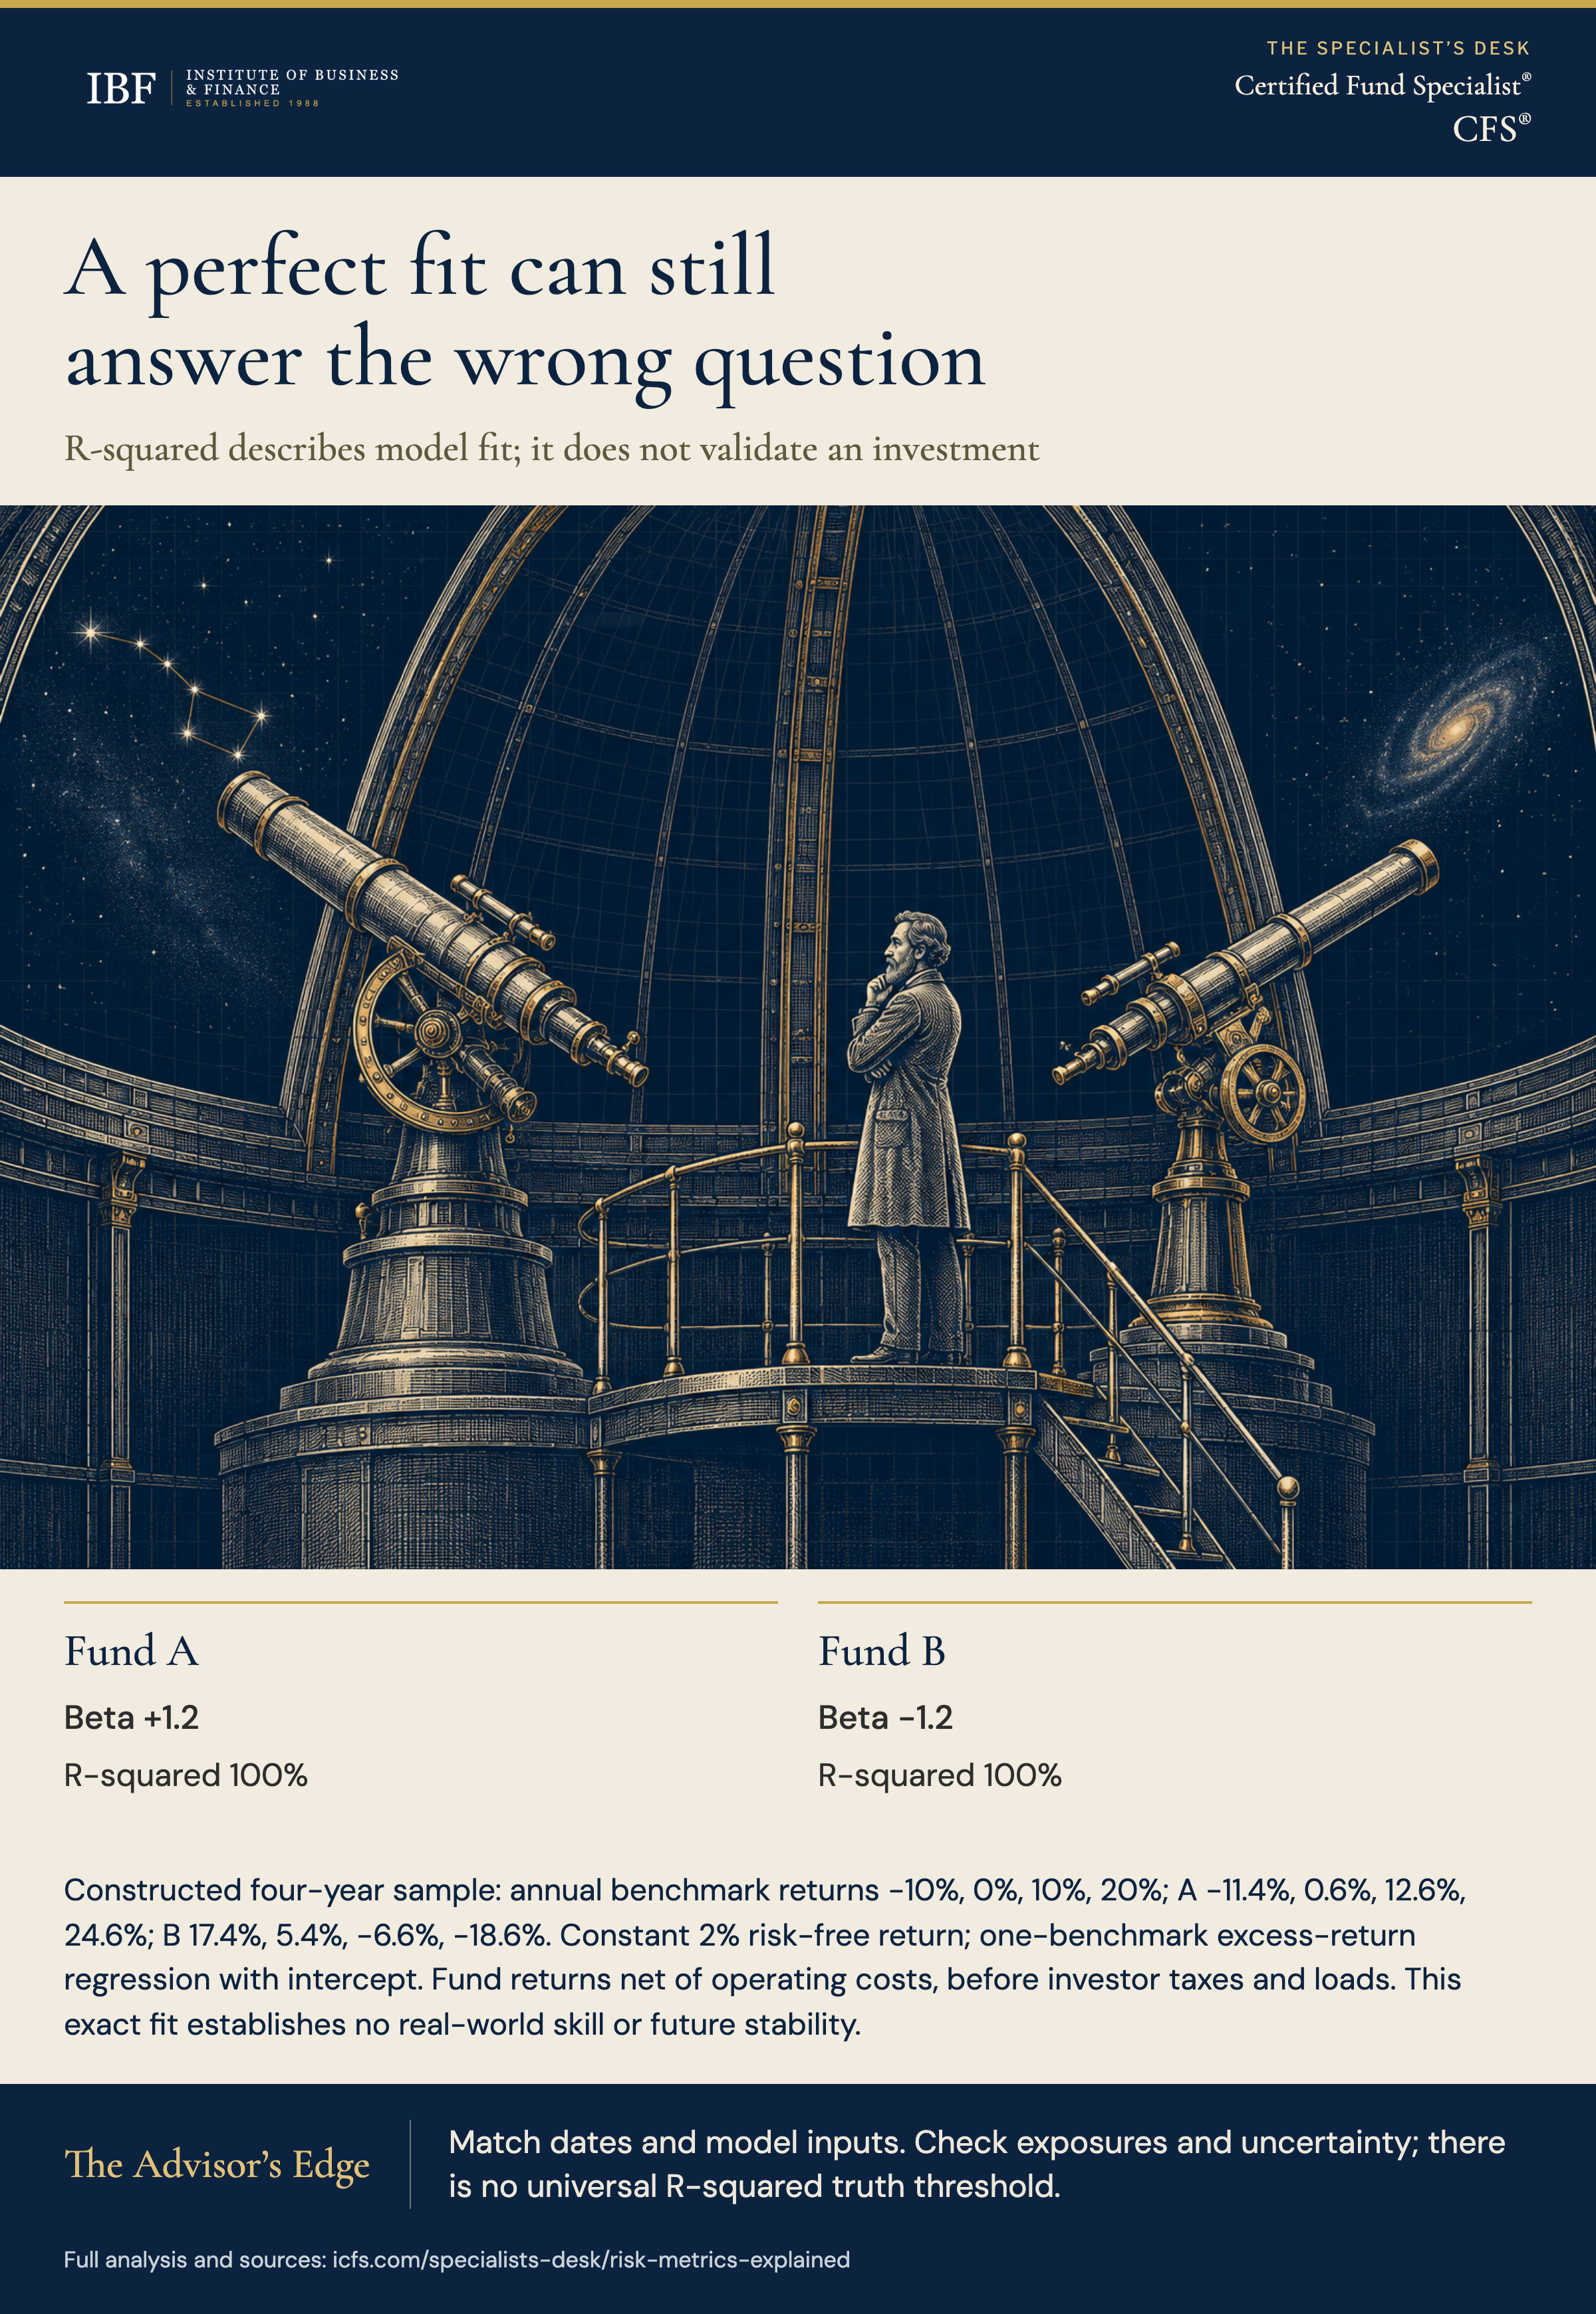
| 1 | -10.0% | -11.4% | 17.4% |
| 2 | 0.0% | 0.6% | 5.4% |
| 3 | 10.0% | 12.6% | -6.6% |
| 4 | 20.0% | 24.6% | -18.6% |
Using arithmetic means and sample standard deviations with denominator three, the benchmark has mean 5.0% and standard deviation about 12.91%. Both funds have standard deviation about 15.49%; Fund A's mean is 6.6% and Fund B's is minus 0.6%.
A one-benchmark excess-return regression gives Fund A beta 1.2 and Fund B beta minus 1.2. Both have fitted alpha of one percentage point per year and R-squared of 100%. The series were constructed to fit those equations exactly. Four invented observations establish no statistical evidence of actual skill or future stability. A zero residual-based error estimate in this constructed fit would be an artifact, not evidence that a real fund's coefficient is known precisely.
Fund B is a useful counterexample to treating high R-squared as validation. Its fit is perfect, yet its benchmark relationship is negative and its mean return is below the assumed risk-free return. The statistic describes fit, not a desirable client outcome.
Sharpe Ratios Need Consistent Inputs
The historical Sharpe ratio is the arithmetic mean of the periodic differential-return series divided by its standard deviation. For the risk-free comparison here, subtract the risk-free return in each matched period. Because the illustration's risk-free return is constant, the excess-return standard deviation equals the total-return standard deviation.
The benchmark's ratio is approximately 0.232: its 3% mean excess return divided by 12.91% standard deviation. Fund A's is about 0.297, using 4.6% divided by 15.49%. Fund B's is about minus 0.168, using minus 2.6% divided by 15.49%. These are descriptive ratios for four annual observations, without additional annualization or a forward forecast.
A higher ratio in a matched positive-excess-return comparison can describe more historical excess return per unit of measured variability. It does not incorporate every risk, the client's liabilities or correlations with other holdings. No universal cutoff establishes that a client has been adequately compensated.
Negative ratios need particular care. Suppose two hypothetical investments both have a 0% arithmetic mean return against a constant 2% risk-free return. If their standard deviations are 5% and 10%, their ratios are minus 0.40 and minus 0.20. The higher numerical ratio arises with greater volatility at the same mean return. It is not an automatic reason to prefer that investment.
If the relevant denominator is zero, check whether the statistic is undefined rather than assigning an attractive score. A smoother series, a shorter lookback or a changed risk-free convention can also affect a comparison without improving the economic investment.
Connect the Statistics to a Feasible Decision
Start with the client's question. Investigating why a portfolio fell requires examining holdings, weights and exposures as well as historical metrics. Investigating a manager's fee requires a comparable benchmark, total costs and evidence beyond an estimated intercept. A spending need requires accessible resources and a plan for adverse outcomes.
Before recommending a switch, compare feasible alternatives with the same starting assets and outside cash. Include taxes, tax-payment funding, distributions, fees and account restrictions under common scenarios and a common endpoint. Do not count a spending reserve as both separate cash and fully invested capital.
This article's invented series is a measurement example, not an allocation or after-tax client comparison. It does not establish which fund should be bought. Historical metrics should inform a funded client analysis rather than replace it.
The Client Conversation
Explain the estimate: "This beta describes the fund's past relationship to this benchmark over these dates. It does not predict every future move. We will check whether the benchmark and holdings fit the question."
Then state the limit: "A positive alpha is unexplained return in a model, not proof of skill. A higher Sharpe ratio summarizes one aspect of the past, not every risk you face."
Finally, connect it to the plan: "Before changing the portfolio, we will review the exposures, costs, tax consequences and cash you need. A statistical ranking alone does not establish a better investment for you."
Key Takeaways
- Match return dates, observation frequency, benchmark, risk-free return and cost conventions before comparing metrics.
- Standard deviation measures dispersion. It is not a complete measure of loss, liquidity or spending risk, and diversification creates no fixed volatility floor.
- Beta is a fitted slope; R-squared is fit. Neither a high fit nor a numeric cutoff proves the model is appropriate or stable.
- Calculate alpha within the stated excess-return model. It is unexplained return, not automatic evidence of manager skill.
- Interpret Sharpe ratios with their inputs, sign and limitations. A higher negative ratio can arise merely from greater variability.
- Treat the statistics as evidence for a client analysis. Actual trades still require feasible funds, equal starting resources, funded taxes and accessible spending money.
The Advisor's Edge
A useful interpretation connects a statistic to the question it can answer and identifies what it leaves out. That requires checking the return series, model and uncertainty before translating a metric into a client decision.
The Certified Fund Specialist curriculum develops risk measurement, expense evaluation and portfolio analysis across two modules and 21 chapters. Apply those skills to the actual holdings and constraints, not a universal threshold. For the distinction between holding count and portfolio risk, see Portfolio Diversification for Risk Reduction.
Sources and Notes: Metric conventions: Morningstar MPT statistics. Alpha's original research setting: Jensen, 1968. Sharpe definition and limits: Sharpe, 1994. The four-year series and negative-ratio example are hypothetical under their stated conventions. Actual provider methodologies and client facts must be checked separately.