Start with the Formula the Client Owns
“Linked to an index” does not tell a client what will be credited. Identify the exact index, observation dates, crediting period, formula, renewal terms and charge structure. A participation percentage on one index is not directly comparable with the same percentage on another.
The calculations below are hypothetical illustrations of specified formulas. They are not current product quotations or a comparison selecting a winning contract. Each assumes the segment is held to its scheduled end with no withdrawals or charges unless expressly stated. Actual contracts can use other methods and adjustments.
Caps, Participation and Spreads
An annual cap of 8%, with 100% participation and a 0% floor, would credit 8% when the measured index gain is 25%. With a measured 5% gain it would credit 5%. The second case disproves the claim that credited interest is never the index return: the credit can equal the measured change when limits do not bind.
With an 80% participation rate, no spread or cap and a 0% floor, a 15% measured gain produces a 12% credit. A 5% gain produces 4%. Participation rates can also exceed 100%; compare the underlying index and all other terms before interpreting that percentage as more market exposure.
A simple spread formula subtracts a stated amount from the measured gain. With a 2% spread, no other reduction and a 0% floor, a 10% gain produces 8% and a 1% gain produces 0%. This illustrates that formula, not a universal order of operations.
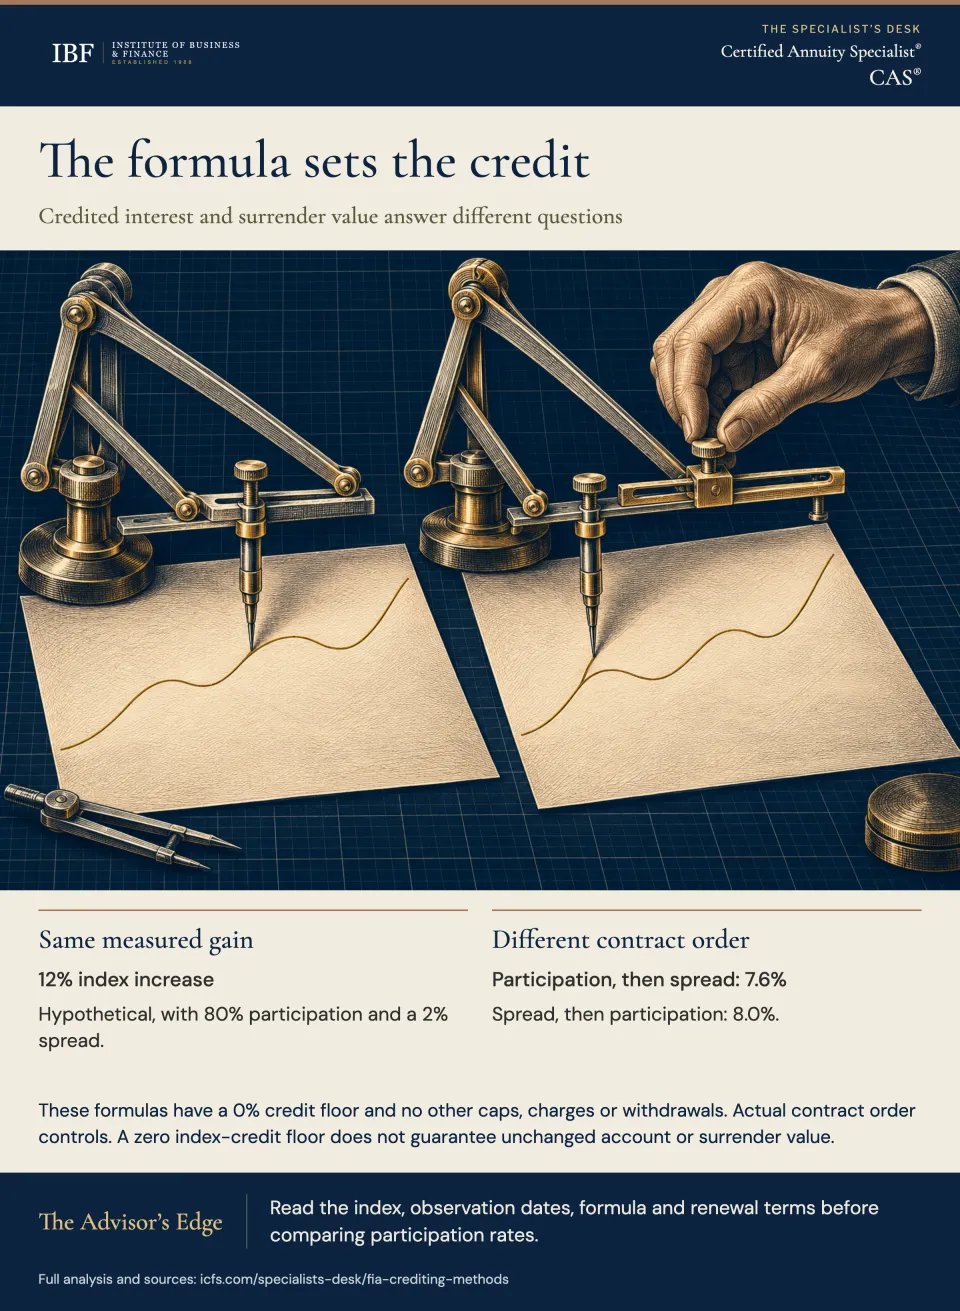
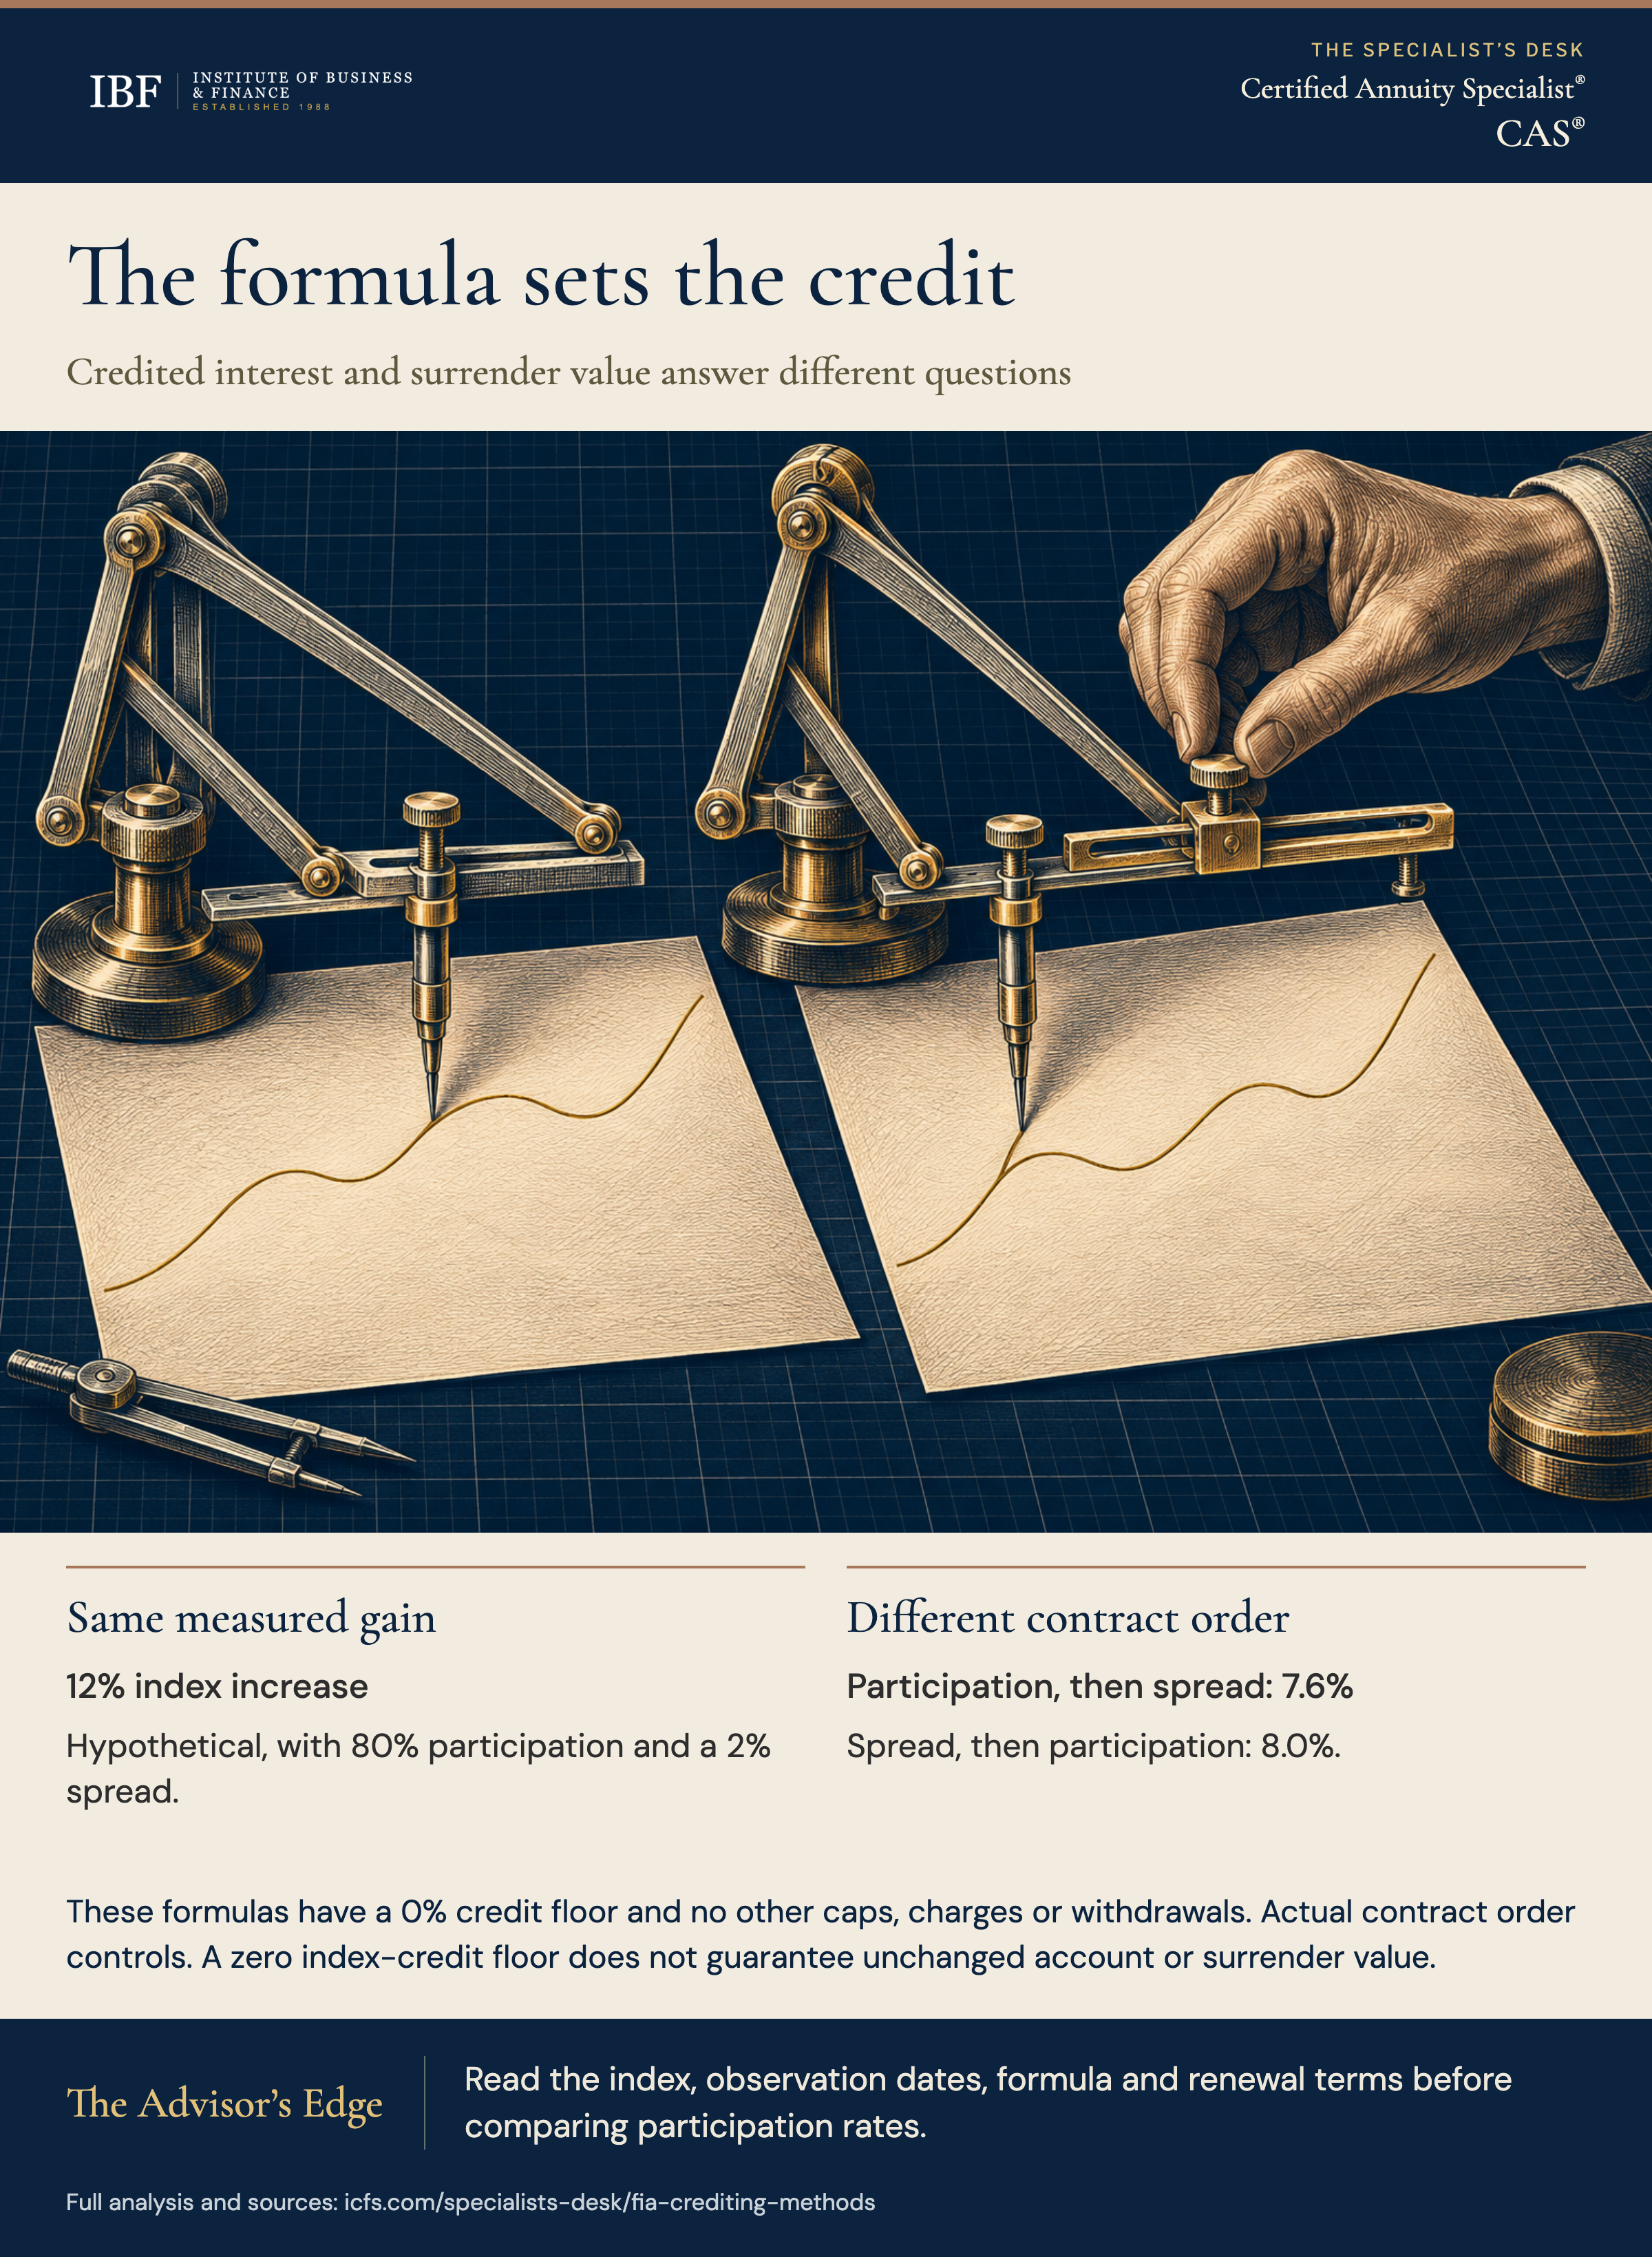
When terms combine, order matters. Applying 80% participation to a 12% gain and then subtracting a 2% spread produces 7.6%. Subtracting the spread first and then applying participation produces 8%. Read the contract instead of choosing the order that produces the more attractive illustration.
Annual Reset Does Not Require Full Index Recovery
Annual point-to-point measures the change between specified annual observations. Under an annual-reset option, the next measurement starts from the reset observation, subject to the contract's terms.
Suppose the index starts at 4,000, falls to 3,000 after the first year and rises to 3,600 after the second. The first change is -25%; the second is +20%. With a zero credit floor, the first segment could credit 0%, and the second could credit on the 20% recovery subject to its cap, participation and other terms. The index remains 10% below the original 4,000.
This demonstrates measurement from a reset point. It does not establish a superior multi-year return, because renewal terms, the full path, charges and alternative investments have not been compared.
Monthly Averaging and Monthly Sum Answer Different Questions
For a hypothetical monthly-average option starting at 5,000, use these twelve observations: 5,100, 5,200, 4,900, 5,000, 5,300, 5,400, 5,200, 5,100, 5,300, 5,500, 5,600 and 5,400. Their sum is 63,000 and average 5,250, giving a 5% measured gain. Point-to-point instead measures 8% from the 5,400 endpoint. Apply each option's remaining terms after measuring its gain.
Averaging is higher than point-to-point whenever its average observation exceeds the endpoint, before other differences in terms. An early spike is not required. Neither measurement method always produces the larger credit.
For a separate monthly-sum example, the monthly changes are +3%, -1%, +2%, +4%, 0%, -2%, +1%, +2%, +3%, -1%, +2% and +4%. Assume each positive month is capped at 2%, negative months pass through unchanged, and a 0% floor applies to the final annual sum. The capped sum is 11%, so the credit is 11% under those terms.
The uncapped arithmetic sum is 17%. That is not the compounded annual index return, which requires multiplying the twelve growth factors. A hypothetical additional monthly zero floor would change this sum to 15%; do not assume a real contract offers that feature without checking. Negative months can offset previously capped positive months even though the final credit has a zero floor.
To make a late-rally comparison reproducible, suppose the first ten monthly observations equal 100, November is 106 and December is 112. The average is 101.5. With no other reductions, averaging measures 1.5%, while annual point-to-point measures 12%. A 10% annual point-to-point cap would produce 10%; a 15% cap on the averaging option would not bind, leaving 1.5%. A larger cap alone did not select the larger credit.
Identify the Index and the Charges
An S&P 500 price-index option measures price changes without dividends. That does not establish that every FIA reference index excludes all dividend or total-return components. Examine the named methodology, including volatility control, excess-return calculations or embedded index deductions. The client generally does not own the index securities or receive their dividends directly.
Do not turn today's dividend yield into a fixed ten-year return gap. A comparison with an index fund requires complete return and dividend paths, fees, taxes, withdrawals and ending values for both alternatives. Forgone index participation is an economic trade-off; it is not necessarily a fee the insurer collects dollar for dollar.
Separately list explicit rider or strategy charges. In a simple counterexample, a $100,000 value with a 0% index credit and an assumed $1,000 charge ends at $99,000 before other changes. A zero credit did not mean zero account-value change. Withdrawals, surrender charges and market-value adjustments can also affect accessible proceeds; insurer claims-paying risk remains relevant to guarantees.
Renewal and Index History Limit a Projection
Check which terms are guaranteed, for how long and within what limits they can change. An illustration assuming the initial cap remains unchanged for decades does not establish that a client will receive those terms. Review the renewal provisions rather than extrapolating the first segment.
For a proprietary index, distinguish live history from pre-launch backtests. Examine asset exposures, deductions and how volatility controls respond to falling and recovering markets. Backtests can involve hindsight or selection bias; that does not prove every designer selected parameters with perfect foresight. Neither a long backtest nor a high participation rate proves an attractive future result.
The Client Conversation
“Let's calculate what this option would credit using its actual index and formula. Then we will show how charges, withdrawals and any early-exit adjustments affect the value you can access. The index floor and your cash surrender value are different things.”
Show an up period, a down period and a recovery period. Ask where an unexpected cash need would be funded during the surrender period. If the answer depends on funds the household does not have, revise the proposed allocation before discussing its illustrated upside.
Key Takeaways
- Identify the exact reference index, observation dates and calculation order.
- Distinguish the measured index change, credited interest, account value and surrender proceeds.
- Use complete monthly or annual inputs before comparing methods.
- Check explicit charges and renewal provisions separately from crediting limits.
- Treat backtests as hypothetical and fund liquidity from actual resources.
The Advisor's Edge
The advisor's contribution is making a contract calculation reproducible and explaining what it does not establish. That includes the accessible cash, renewal uncertainty and trade-offs with feasible alternatives.
The Certified Annuity Specialist® (CAS®) designation covers annuity evaluation and indexed-crediting concepts. Apply those skills to the actual contract rather than converting an illustrated credit into a promise of safety or superior results.
For a related contract-level discussion, see RILA Buffer vs. Floor Mechanics: When Each Protection Strategy Works.
Sources and Notes: Hypothetical calculations; reviewed November 13, 2026. SEC, Indexed Annuities; Texas Department of Insurance, Annuities Guide; DC Department of Insurance, Guide to Understanding Annuities.