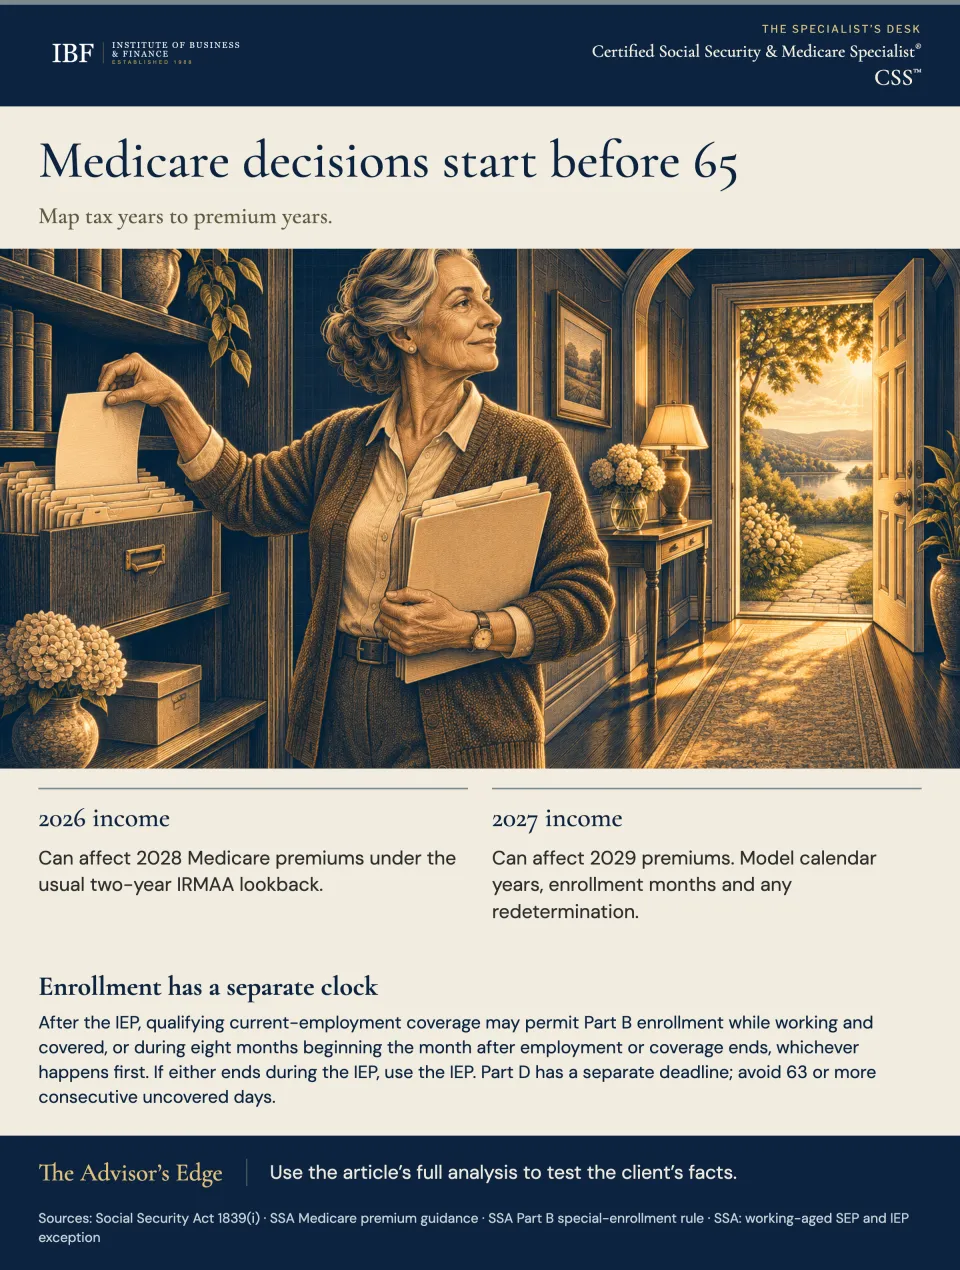
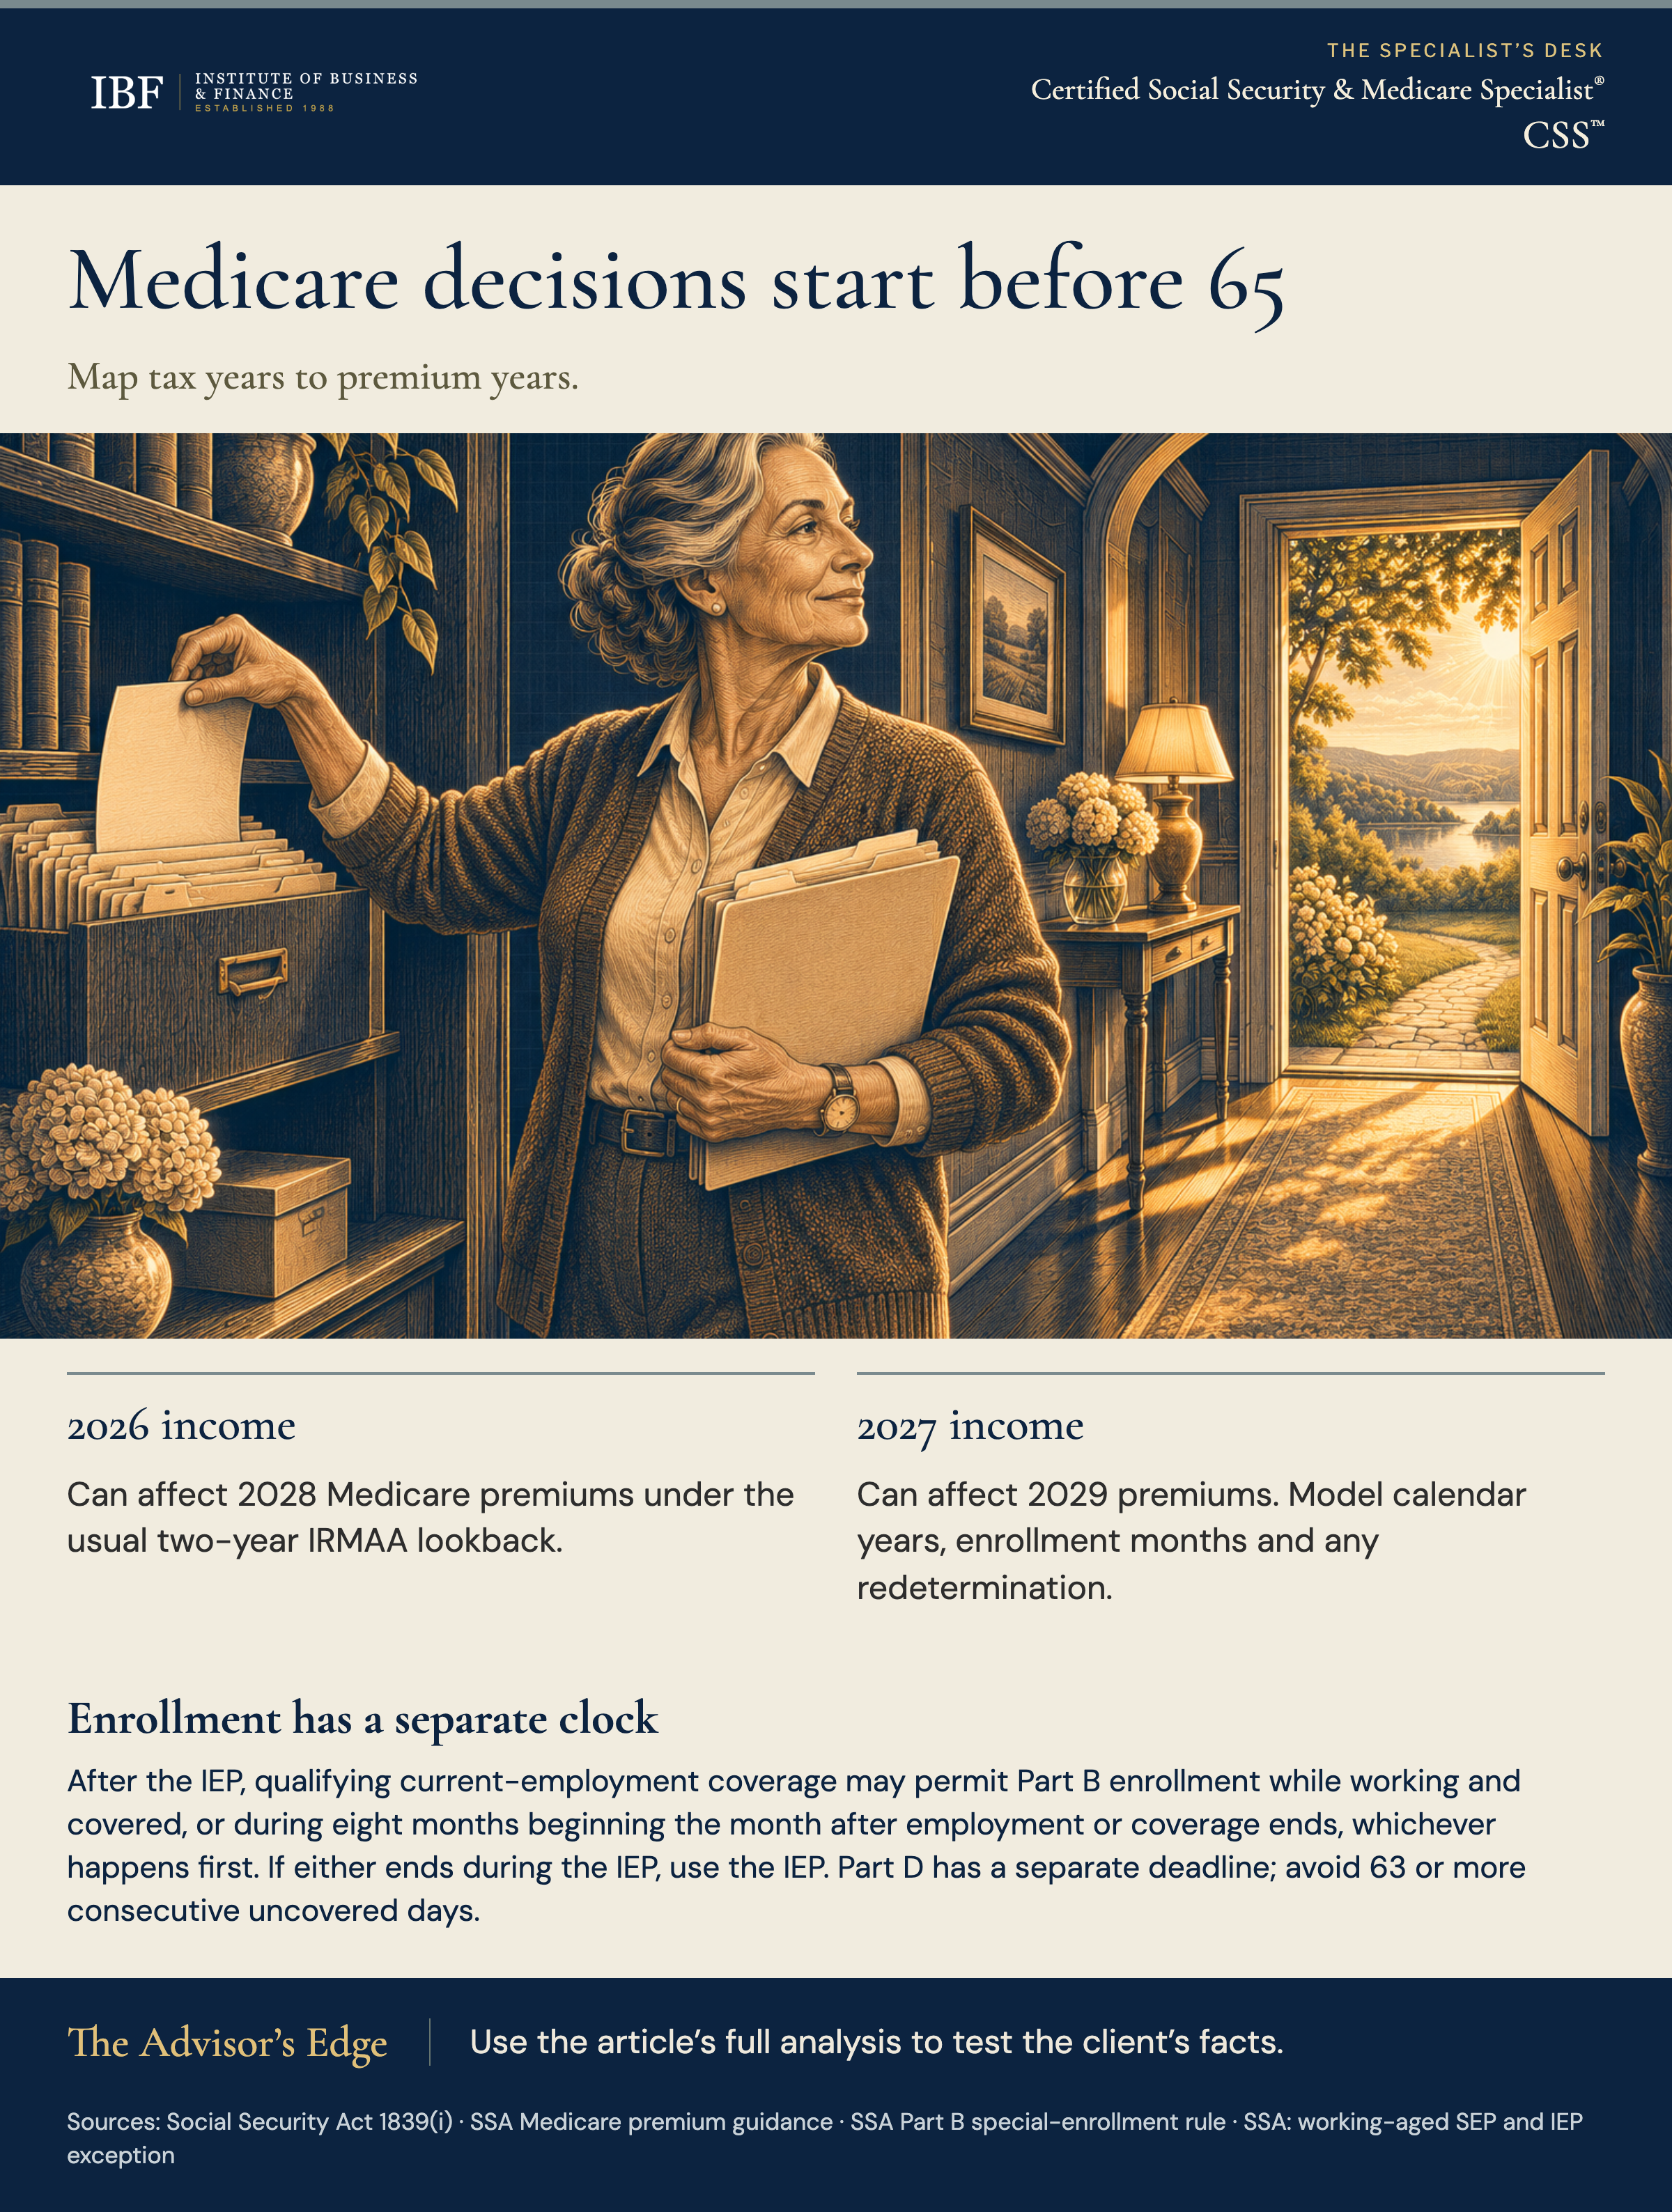
The Medicare Enrollment Stakes
A client delays Medicare at 65 and revisits the decision three years later. The result depends on the coverage history: a qualifying enrollment exception may avoid a penalty, while another client can face a gap or penalty. Confirm the history before calculating the cost.
For a first Part B enrollment on or after January 1, 2023, SSA generally counts months after the initial enrollment period ends through the enrollment month, excluding applicable months. The penalty is generally 10% of the standard premium for each full twelve countable months. Reenrollment and earlier enrollment rules can differ. Part D uses a separate coverage test and calculation; model actual dates rather than applying a blanket lifetime estimate.
This is where the CSS designation adds the most direct value. Eligible workers generally can start their own retirement benefits from 62 onward; delayed retirement credits stop at 70. Spousal and survivor benefits follow different rules. Medicare does not work that way. Medicare operates on rigid enrollment windows. Check the actual delay and any exception before calculating a penalty; a missed date does not always create a lifetime charge.
The second layer of complexity sits in IRMAA. Higher-income clients face surcharges on both Part B and Part D premiums based on income from two years prior. This two-year lookback creates a planning window if you know how to use it.
This article walks you through both layers: the enrollment periods themselves and the income management strategies that reduce IRMAA exposure without sacrificing retirement security.
The Initial Enrollment Period: Your Client’s Primary Window
The age-65 IEP generally runs from three months before the birthday month through three months after it. A birthday on the first day of a month shifts that seven-month window one month earlier. Confirm the exact eligibility and enrollment dates rather than applying the ordinary birthday-month rule to every client.
Margaret turns 65 on June 15. Her IEP runs March 1 through September 30. Robert turns 65 on April 1, so his IEP shifts one month earlier: December 1 through June 30. His age-based Medicare eligibility begins March 1. Enrolling during December, January or February allows coverage to begin March 1; enrolling in March or later generally starts Part B the following month.
The specific enrollment month matters because it determines when coverage begins:
- For Part B and premium Part A, enrolling in the first three months of the IEP generally starts coverage in the first eligibility month; first-day birthdays move that month earlier
- For Part B and premium Part A, enrolling in the last four months of the IEP generally starts coverage the following month; premium-free Part A has separate retroactive-start rules. The later in the IEP you enroll, the longer the gap, up to four months if you wait until the last month of your IEP.
Patricia turns 65 on June 15. For Part B and premium Part A, enrollment in March, April or May generally starts coverage June 1; June enrollment generally starts July 1, and August enrollment generally starts September 1. Premium-free Part A has different effective-date and potential retroactivity rules. Confirm which coverage the client needs.
This timing matters most for clients without other health coverage. Those with employer coverage may tolerate the gap. Those retiring at 65 with no employer plan cannot.
Automatic vs. Voluntary Enrollment
People receiving Social Security or Railroad Retirement Board benefits sufficiently before age 65 generally receive Parts A and B automatically. Residents of Puerto Rico must enroll in Part B separately. Confirm the Medicare card and effective dates, especially when benefits begin close to age 65.
This automatic enrollment creates a critical decision point. If a client has employer coverage and wants to delay Part B, they must actively decline it. Inaction means enrollment and premium deductions from Social Security. This matters especially for clients with qualifying employer group health coverage (through their own or a spouse’s employment with 20+ employees).
Clients who will not be enrolled automatically generally must apply. Verify Social Security or Railroad Retirement Board status, residence and the actual Medicare notice or card. Apply early in the exact IEP when coverage is needed from the first eligibility month; first-day birthdays shift that month earlier.
This distinction between automatic and voluntary enrollment is where many clients stumble. A client pursuing delayed claiming of the worker's own retirement benefit, potentially to increase the monthly benefit through age 70 may not realize that Medicare requires separate action. They assume “Medicare will take care of itself” when Social Security is claimed later. It does not work that way. Medicare eligibility and Social Security claiming are linked administratively but separable in timing.
When Employer Coverage Changes the Rules
Qualifying current-employment group coverage may permit a Part B SEP after the IEP. Eligible clients can generally enroll while working and covered, or during the eight months beginning the month after employment or that coverage ends, whichever happens first. Generally use the IEP for enrollment during it; do not assume the working-aged SEP applies. Prior disability entitlement and other coverage histories can create exceptions, so confirm the period with SSA.
- The client has qualifying group coverage based on their own or their spouse’s current employment; verify the coverage history from the first month of Part B eligibility and SSA’s permitted-break and subsequent-SEP rules
- The coverage is through current employment (not COBRA, retiree coverage, or former employer benefits)
- They enroll in Part B while eligible or within the eight-month period beginning the month after employment or qualifying coverage ends, whichever happens first
This Special Enrollment Period is the most important exception to the penalty rules you will encounter with working clients.
Consider a client working until 68 with a qualifying current-employment group health plan. Enrollment is generally available while qualifying coverage continues. With one qualifying plan, the eight-month period generally begins after the month employment or that coverage ends, whichever happens first. For overlapping plans or interruptions, verify SSA's last-qualifying-coverage rules. COBRA and retiree coverage do not extend the ordinary clock. Confirm who pays first and coordinate the separate Part D deadline; the Part B SEP does not protect a 63-day drug-coverage gap.
The employer size matters. For age-based Medicare, Medicare generally pays first for a single-employer plan with fewer than 20 employees. Multiple- or multi-employer arrangements can differ; confirm coordination with the plan before delaying Part B. The client should enroll during their IEP to avoid complications.
SSA generally needs evidence of qualifying employment and group coverage for the working-aged Part B SEP. Form CMS-L564 is commonly used; alternative evidence can be available when an employer cannot complete it. Gather coverage and employment dates before leaving the job and confirm SSA’s requirements.
The General Enrollment Period Safety Net (and Its Costs)
Clients who miss their IEP can still enroll during the General Enrollment Period, which runs January 1 through March 31 each year. Coverage begins the first day of the month after enrollment. This timing reflects a 2023 rule change; previously, GEP enrollees waited until July 1 for coverage to begin.
But the GEP comes with a cost. GEP enrollees may owe a Part B penalty, generally 10% of the standard premium for each full applicable twelve-month period. Check countable months, excluded coverage and available relief.
Part B generally adds 10% of the standard premium for each full twelve-month period of countable delay, subject to exceptions. Missing an IEP by a few months does not automatically create a twelve-month penalty. Determine the actual IEP, any qualifying coverage and SEP, and the enrollment date before calculating the penalty.
For someone who must buy Part A, a late-enrollment penalty may add 10% for twice the applicable number of full years delayed. Premium-free Part A has no Part A late-enrollment premium penalty. Part B and Part D penalties generally continue while the relevant coverage is held, subject to applicable relief or reset rules.
A client whose ordinary October-birthday IEP ends January 31 can still enroll during the February or March GEP that same year, with Part B generally effective the following month. If March 31 also passes and no SEP applies, the next GEP starts the following January. Calculate any penalty from the actual full twelve-month delay periods; a short coverage gap alone does not establish one.
Part D Penalties: A Separate Calculation
Part D (prescription drug) enrollment follows similar logic but uses a different calculation. The penalty equals 1% of the national base beneficiary premium for each full month of delay without creditable coverage. The national base beneficiary premium is $38.99 for 2026 and the announced $41.33 for 2027. Use the premium year being modeled; this is not an individual plan's premium. This base premium is recalculated annually, so penalty dollar amounts change each year.
Assume 18 full countable uncovered months and no exception. The Part D percentage is 18% of the national base beneficiary premium, not the chosen plan’s premium. In 2026, $38.99 times 18% is $7.0182, rounded to $7.00 monthly and added to the plan premium. The amount can change annually; exceptions apply.
Confirm that the prescription coverage is creditable. Qualifying employer or union coverage, TRICARE or VA coverage can generally permit Part D delay without a penalty while it continues. For loss of employer or union coverage, verify the enrollment opportunity, generally two full months after the month it ends, and the new plan's effective date. Avoid 63 consecutive uncovered days after the IEP, subject to exceptions. An application window does not guarantee continuous coverage. Ask the benefits administrator whether joining Part D would end health or drug benefits for the client or dependents.
Ask the plan or benefits administrator for drug coverage's creditable status and keep applicable notices and coverage dates. A notice may say coverage is not creditable and does not alone prove continuous coverage. Disclosure duties depend on the arrangement and coverage year; the 2027 final rule exempts account-based plans such as HRAs and ICHRAs for coverage beginning in 2027. Confirm the actual drug coverage and plan its transition rather than treating a notice as blanket permission to delay.
The surprise for many clients: employer coverage ends, they assume it transitions automatically, and they do not realize a gap exists. When they eventually enroll, they discover they owe years of penalty surcharges. This is one of the most common sources of preventable cost in Medicare.
The Annual Election Period and Coverage Changes
Existing beneficiaries face a different enrollment window each year. The Open Enrollment Period runs October 15 through December 7. During this time, beneficiaries can:
- Switch from Original Medicare to Medicare Advantage
- Switch from Medicare Advantage to Original Medicare
- Change from one Medicare Advantage plan to another
- Change Part D plans
Changes take effect January 1. A beneficiary who changes plans in November still has about six weeks before the change takes effect, allowing time to get their affairs in order.
Separate from the annual fall window, Medicare Advantage enrollees generally have a January 1-March 31 Medicare Advantage Open Enrollment Period to make a permitted change. Before returning to Original Medicare, confirm Part D coverage and any desired Medigap policy's availability, underwriting, guaranteed-issue rights and state protections. The annual Medicare change window is not a new guaranteed Medigap enrollment window.
Use this annual window in your client relationships. Schedule Medicare reviews in September, before the October OEP begins. This allows time to analyze options, compare plans, and make deliberate decisions instead of rushing in early December.
Managing IRMAA: The Income Timing Game
Income-Related Monthly Adjustment Amounts apply a surcharge to both Part B and Part D premiums for beneficiaries with income above certain thresholds. The critical detail: SSA generally uses tax information from two years before the premium year. Medicare MAGI generally means adjusted gross income plus tax-exempt interest; check the return, filing status and any redetermination.
SSA generally uses 2024 tax-year MAGI for 2026 IRMAA. If unavailable, it may temporarily use 2023 information. A client retiring in 2026 may owe IRMAA based on earlier working income if the applicable threshold was exceeded; a qualifying reduction can support a request to use a more recent year.
For 2026, the standard Part B premium is $202.90 monthly. IRMAA generally begins above $109,000 for individual filers or $218,000 for joint filers. Full Part B adjustments range from $81.20 to $487.00 monthly. Part D has a separate $14.50 to $91.00 adjustment when applicable; combined full Part B and Part D adjustments range from $95.70 to $578.00.
But the two-year lookback also creates a planning window. Clients can manage their MAGI in years that will affect their future Medicare premiums.
Roth Conversions and the Lookback Window
Consider a client with a $1.2 million traditional IRA who plans to retire at 65. The balance alone does not establish future MAGI or IRMAA. Model taxable withdrawals and conversions, other income, filing status, enrollment months and the relevant thresholds.
Map each conversion to its tax year and ordinarily to the Medicare premium year two calendar years later. If the client turns 65 in 2029, taxable income in 2027 can affect 2029 premiums even when a conversion occurs before the 63rd birthday. Age alone is not a safe cutoff. Model the full return, enrollment months and any qualifying redetermination before comparing premium costs.
A smaller traditional IRA can reduce later taxable distributions, and qualified Roth IRA distributions generally do not enter Medicare MAGI. That alone does not prove a conversion benefit. Start conversion and no-conversion paths with the same IRA and outside cash. Include conversion-tax funding, IRA basis, required distributions, returns, fees, future withdrawal taxes, IRMAA for each enrolled person and month, liquidity and after-tax assets at a common end date. RMDs themselves cannot be converted.
Life-Changing Events and IRMAA Appeals
The two-year lookback is not absolute. Clients who experience certain life-changing events can request IRMAA redetermination using Form SSA-44. Qualifying events include:
- Marriage, divorce or annulment, or death of a spouse; a qualifying event and applicable income or filing-status change may support lower IRMAA, but do not guarantee relief
- Work stoppage or work reduction associated with a qualifying income decrease
- Loss of income-producing property (disaster, fraud). Note: voluntary sale or transfer of income-producing property does not qualify. The loss must be involuntary and beyond the client’s control.
- Loss of pension income from a qualifying termination, reorganization or scheduled cessation of the pension plan, as specified by SSA
- Employer settlement payment received due to an employer’s bankruptcy, closure, or reorganization
This is particularly valuable for new retirees whose current-year income is dramatically lower than the lookback year. A client who retired in January 2026 may receive an IRMAA surcharge based on their 2024 working income. But they can request redetermination based on their reduced 2026 income.
The process requires documentation of both the life event and the income change. Flag this opportunity for any client whose circumstances have changed significantly.
IRMAA Planning Intersects with Tax Planning
IRMAA thresholds do not align with federal tax brackets. A client might have room in the 22% tax bracket but find that filling it triggers the next IRMAA tier. An IRMAA increase can outweigh the projected future tax benefit of recognizing income now. Compare total current and future taxes, premiums and after-tax resources.
When doing tax projection work for Medicare-enrolled clients, add a row for IRMAA impact. The true marginal rate on additional income includes not just federal and state taxes but also potential IRMAA surcharges.
Coordinating Medicare Enrollment with Social Security Decisions
This is where the CSS designation’s value becomes clear. Social Security and Medicare are administratively linked but strategically separable.
Automatic enrollment depends on benefit timing, residence and other eligibility facts. People receiving Social Security or Railroad Retirement benefits sufficiently before 65 generally receive Parts A and B automatically; Puerto Rico and foreign-residence Part B rules require separate attention. Verify the card and effective dates rather than assuming enrollment from claiming status alone.
Scenario 1: Claiming Social Security Before 65
First confirm the benefit-entitlement timing, residence, Medicare card and effective dates. Where Parts A and B enrollment will occur automatically, review employer coverage and whether declining Part B is appropriate. Follow the notice’s instructions and confirm any declination; do not assume every Social Security recipient has the same automatic-enrollment treatment.
Scenario 2: Delaying Social Security, Enrolling in Medicare at 65
The client wants a higher monthly own-record retirement benefit by delaying claiming and Medicare coverage at 65. Whether delay improves the household outcome depends on longevity, survivor benefits, funding and other circumstances. They must apply for Medicare separately through ssa.gov or a Social Security office. They select Medicare enrollment without Social Security. Part B premiums are paid directly (not deducted from a Social Security check that does not exist yet).
This dual timing is counterintuitive but powerful. A client can claim Social Security at 70 while having had Medicare coverage for five years.
Scenario 3: Delaying Both Past 65
Working-aged SEP eligibility depends on qualifying current-employment group coverage and the coverage history from first eligibility; do not assume that acquiring employer coverage later cures an earlier gap. Confirm SSA’s continuous-coverage and interruption rules. When eligible, enrollment is generally available while working and covered and for eight months beginning the month after employment or coverage ends, whichever occurs first. Generally use the IEP for enrollment during it; prior disability entitlement and other coverage histories can create exceptions. Confirm the applicable period with SSA. Part D has its own deadlines and creditable-coverage test.
The Client Conversation: When to Bring Up Medicare
Most of your clients turn 65 thinking about Social Security. Medicare feels like a separate issue. Your job is to connect them.
Start before the first Medicare decision or relevant lookback year. Explain: "Medicare has its own enrollment rules. A delay may fit qualifying current-employment group coverage, but we must verify the actual arrangement, who pays first, your enrollment period and HSA consequences. An ICHRA does not qualify for this working-aged SEP. We will coordinate these dates separately from Social Security claiming."
Run specific scenarios using the client's actual notices: “We will confirm whether Parts A and B will start automatically and their dates. If you delay Social Security, check whether you need a separate Medicare application. Then verify any working-aged Part B SEP, the separate Part D rules and countable penalty months.”
For clients with employer coverage, track the employment end date and the coverage end date separately. Explain which pays first, when the Part B SEP ends and when Part D coverage must start. COBRA or retiree coverage does not restart the Part B clock.
Create a timeline with the exact IEP, coverage effective dates, planned Social Security claim, eligible Part B SEP and separate Part D deadline. First-day birthdays can shift the age-65 window. If the client contributes to an HSA, coordinate the last eligible contribution month with Medicare enrollment: retroactive Medicare coverage can make contributions for those months excess. Do not assume declining Part B alone preserves HSA eligibility.
Key Takeaways
- Establish the exact IEP and coverage-start dates; a first-day-of-month birthday shifts the age-65 window earlier.
- Verify current-employment coverage and SEP eligibility separately from employer-size payer coordination. If coverage or employment ends during the IEP, do not assume the working-aged SEP applies.
- Treat Part D creditable coverage, its enrollment opportunity and its coverage-effective date separately from the Part B clock. Avoid 63 or more consecutive uncovered days after the IEP.
- Map each conversion or other income item from its tax year to the generally applicable premium year two calendar years later; age alone is not a safe cutoff.
- Calculate penalties and IRMAA from countable periods, filing status and current thresholds, then check exceptions and any qualifying SSA-44 redetermination.
The Advisor’s Edge
The Medicare enrollment rules are not hidden. The IEP window, SEP rules, and penalty calculations are all published by CMS and the Social Security Administration. Any advisor with a calculator and a form can look up the timelines.
Running client-specific scenarios in advance can turn a vague enrollment suggestion into a documented plan. Record eligibility, countable penalty months, effective dates, coverage coordination and the next action. A specific calculation is more useful than a blanket promise about lifetime savings.
The Certified Social Security and Medicare Specialist™ (CSS™) designation is where financial professionals develop the competence to guide clients through these enrollment decisions with precision, connecting Medicare timing to Social Security strategy in ways that serve clients on Monday morning.
For related Social Security planning, see Maximizing Social Security Benefits for Married Couples.
Sources and Notes: Authorities reviewed November 12, 2026. Medicare Part B penalty; Medicare enrollment periods; SSA-44 life-changing event form; SSA working-aged SEP; SSA Part B penalty exceptions; CMS Part D guidance; SSA Medicare premiums; Medicare coverage dates. Product terms and client facts control the application; numerical illustrations use the assumptions stated in the article.