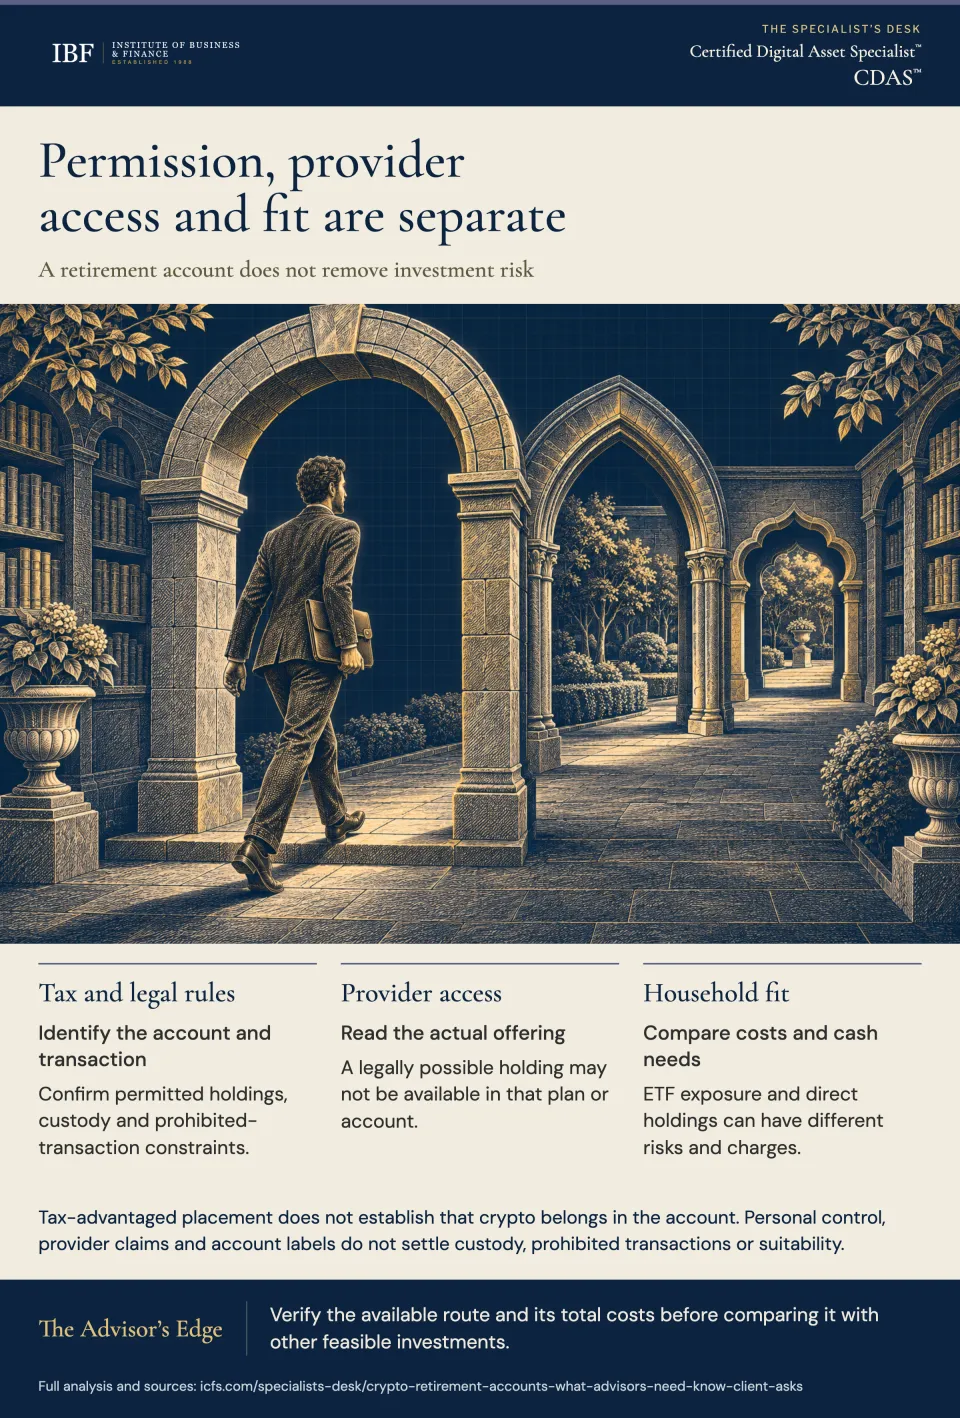
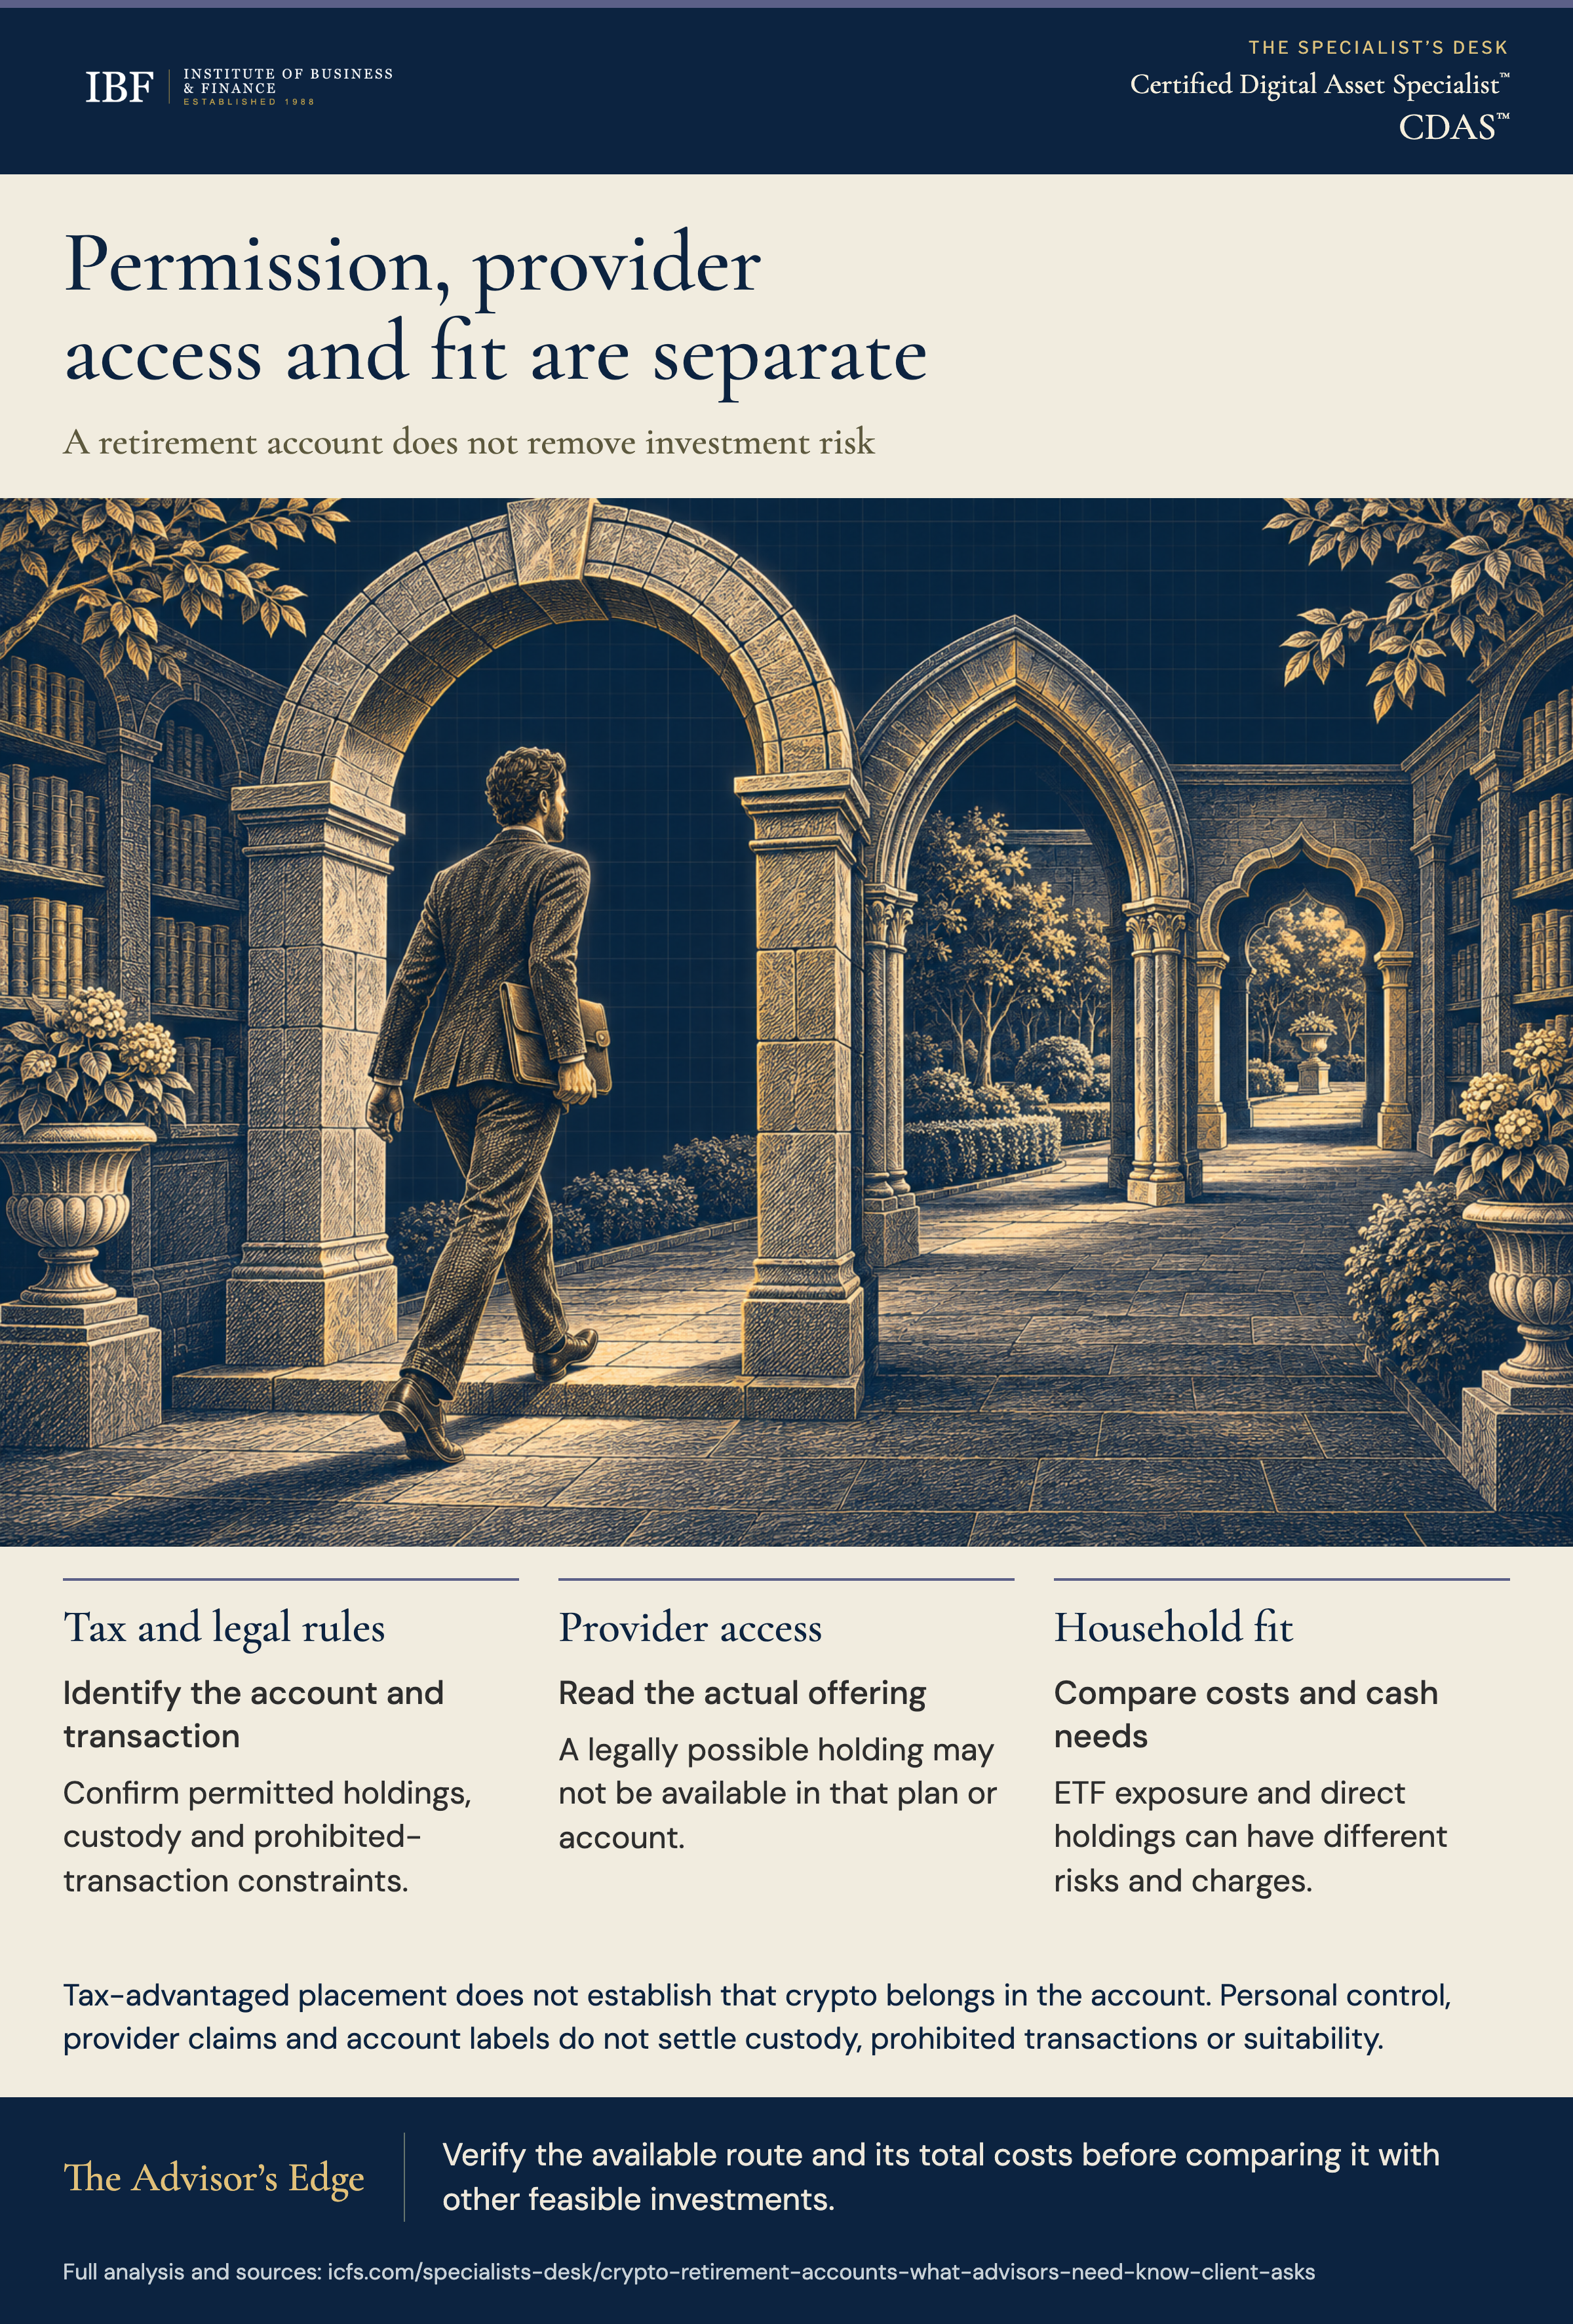
1. Separate investment access from a recommendation
First decide whether any digital exposure serves the client's plan. Identify essential spending, accessible reserves, existing holdings, loss capacity and investment purpose. Compare zero with feasible alternatives before choosing an account. A new product on a platform does not make it appropriate for every participant or every IRA owner.
On May 28, 2025, the Department of Labor rescinded its 2022 crypto-specific release and returned to a neutral approach. ERISA fiduciary duties still apply. Executive Order 14330 directed review and appropriate action concerning alternative assets; it did not itself add an investment to every plan or remove prudence requirements. DOL announced a proposed rule in March 2026. On November 5, 2026, a final-rule-stage submission was received for OIRA review; as of November 13 it remained pending review. A submission for review is not an effective final rule. Check the current rule and effective date before an actual plan decision.
Employer adoption, recordkeeper capabilities, plan documents and account permissions remain practical constraints. A participant should verify the current menu or brokerage-window terms before counting a proposed holding as available. Do not use an executive order or a provider's advertised maximum as the individual's approved allocation.
2. Exchange-traded exposure delegates coin handling
A permitted spot bitcoin or ether ETP may provide price exposure through a brokerage retirement account. The IRA holds product shares while the product arranges its underlying custody. That can reduce the investor's need to manage keys directly, but the product still carries underlying-asset, custody, market, operating and legal-structure risks.
Read the current prospectus and account rules. Identify annual charges, trading costs, tracking, tax treatment, staking if any and the protections actually applicable. Spot crypto commodity trusts are not automatically investment companies registered under the Investment Company Act of 1940 merely because their shares trade on an exchange.
Not holding a private key does not make every transaction involving an IRA permissible. Personal use, related-party dealings or other prohibited arrangements require separate analysis. Likewise, brokerage availability does not mean coins can be withdrawn in kind to a personal wallet or used for purchases without distribution consequences.
3. Direct-holding IRAs require documented custody and costs
A self-directed arrangement can offer assets unavailable through a particular ETP. Confirm the custodian's actual authority, the assets permitted and the holder's rights. Marketing terms such as “qualified,” “insured” or “checkbook control” do not establish that every custody arrangement complies with IRA requirements or that insurance covers the contemplated loss.
Collect the entire schedule: acquisition and sale fees, spreads, recurring custody or account charges, minimums, transfer and exit costs. Compare the same investment amount, holding horizon, trading schedule and returns. Transaction fees and annual asset charges cannot be ranked merely by comparing their percentages; the bases and frequencies differ.
For example, assume two permitted hypothetical routes, each starting with $10,000 and held for five years, with zero gross investment return, no tax, no additional cash flows, and no spread or other charges. Route A has only a 0.25% annual charge deducted from assets at each year-end. Route B has only an entry charge equal to 1% of the starting $10,000, deducted before purchase, and an exit charge equal to 1% of the final sale proceeds, both paid from the assets. These invented schedules illustrate fee mechanics, not actual products or equal custody protections.
Route A ends with $10,000 × 0.9975⁵ = approximately $9,875.62. Route B invests $9,900 after the initial charge and yields $9,801 after the final charge. Route A is $74.62 ahead under these assumptions. If the horizon is instead ten years with the same zero return and no intermediate trades, Route A ends near $9,752.79 while Route B still yields $9,801, reversing the result. Actual recurring fees, trades, returns and restrictions could change either comparison. Lower fees also do not resolve custody or suitability.
4. Explain McNulty without turning analogy into a holding
In McNulty v. Commissioner, the Tax Court held that Mrs. McNulty's receipt and unfettered possession of IRA-funded physical American Eagle coins caused taxable distributions equal to their cost. The opinion also records prohibited transactions involving Mr. McNulty's separate IRA; the IRS conceded that Mrs. McNulty had not engaged in a prohibited transaction with respect to her IRA, its LLC investment or the coin purchases. It was not a decision about a cryptocurrency hardware wallet.
Applying that reasoning to personal control of IRA-funded crypto is an uncertain, fact-specific inference rather than a crypto-specific holding. Obtain qualified advice before moving IRA assets into a personally controlled wallet. Do not assure the client that an LLC or a custodian's account opening makes every later transfer compliant.
Separately, an IRA owner's or beneficiary's prohibited transaction can cause the IRA to cease qualifying and a deemed distribution under the statutory rules. That is distinct from a distribution of particular assets. Taxable amount, IRA basis, Roth qualification and possible early-distribution exceptions also require analysis. “Touch the keys and the entire account is automatically taxed plus 10%” overstates the cited case and collapses different rules.
5. Compare Roth, traditional and taxable ownership fairly
A qualified Roth IRA distribution generally can be tax-free, but qualification and funding matter. A conversion may require current tax, and that tax must be included even if paid from another account. Using scarce Roth capacity for a loss also has an opportunity cost. Conviction about upside alone does not establish the best location.
Traditional IRA distributions generally are taxable to the extent included in income, with any basis and applicable rules taken into account. A taxable investment's capital-gain rates, realized-loss use and potential inherited-property basis adjustment create different outcomes. An inherited traditional IRA is not automatically all taxable if it contains basis, and taxable property does not receive an identical basis adjustment in every situation.
Start account-location comparisons with the same total household resources and target spending or beneficiary outcome. Include conversion tax and funding, return paths, fees, withdrawal timing, tax rates, loss availability and terminal after-tax value. A hypothetical high-return path can favor one location and a loss or lower future tax rate another. Do not recommend traditional IRAs rarely or Roth routinely without the complete comparison.
6. Test spending, trading and plan execution separately
Selling an investment inside a retirement account and distributing proceeds out of the account are different actions. An investor may trade a permitted product without an immediate personal withdrawal, while spending or moving assets outside the account can create tax and additional-tax questions. Check hours, settlement, permitted orders and distribution procedures before promising immediate liquidity.
For a retirement plan, analyze how an adverse path affects withdrawals and remaining resources. In a narrow illustration with other assets unchanged and no rebalancing, a 15% initial position losing 70% subtracts 10.5 percentage points of initial portfolio value. That is a position contribution, not the entire portfolio's maximum loss. A small holding's gain is likewise not proof of overall retirement adequacy.
A counterexample to direct-holding access is a client who cannot maintain the required custody discipline or whose actual costs exceed a permitted alternative without providing a useful benefit. A counterexample to automatic ETP selection is a client whose account prohibits the product or whose specific objective cannot be met by its terms. The answer can also remain no exposure. Document the available funding, restrictions and decision rather than assume a contribution or rollover can always supply the desired amount.
The Client Conversation
“Can I hold crypto in my retirement account and control the wallet?”
“We need to check what your account permits and who must hold the assets before changing custody. Then we can compare full costs, tax treatment and access with other permitted routes, including no exposure.”
7. Key Takeaways
- Establish investment purpose and loss capacity before selecting an account.
- Verify plan permissions independently from regulatory announcements.
- Compare complete fee schedules over the same trades and horizon.
- Distinguish McNulty's physical-asset holding from a crypto analogy and IRA disqualification.
- Model Roth, traditional and taxable routes from equal total resources.
- Separate internal trading from external distribution and spending access.
The Advisor's Edge
The Certified Digital Asset Specialist™ (CDAS™) program connects digital markets, custody, taxation and portfolio integration. An advisor can help the client identify a permitted route and compare its complete economics with alternatives. A defensible recommendation explains costs, control and account consequences without treating easier access as a reason to invest or one court case as a universal rule.
For the related vehicle and custody analysis, see Bitcoin and Crypto ETFs: A Practical Guide for Financial Advisors.
Sources and Notes: Reviewed November 13, 2026. Fee and loss cases are hypothetical. DOL, May 2025 Rescission; OIRA, Pending Final-Rule Review; DOL, March 2026 Proposal; Tax Court, McNulty opinion; IRS, IRA Prohibited Transactions; IRS Publication 590-B; IRS Publication 551; SEC, Bitcoin and Ether ETP Bulletin.